Inner Circle | Nov 2026
SEC Item 402 Proposal: Rollbacks to Executive Compensation Disclosures
Part 3 of 3: Proposed changes to termination benefits, equity grants, director pay, and XBRL tagging would reduce required disclosures without eliminating underlying oversight responsibilities.
Editor's note: On November 13, 2026, the Securities and Exchange Commission (SEC) proposed sweeping amendments to Item 402 of Regulation S-K (the “Proposal”), representing the most significant reconsideration of executive and director compensation disclosure since the 2006 amendments. This three-part series explores the potential new core disclosure framework; major calculations and high-burden disclosures that would be simplified; and disclosures that would be eliminated or substantially streamlined, while underlying governance responsibilities remain.
The SEC’s Proposal would eliminate or streamline several executive compensation disclosure requirements, from termination payments and pension benefits to compensation risk and equity grant timing. While these changes could significantly reduce reporting obligations, many of the underlying governance responsibilities would remain.
Proposed Changes: At a Glance
Topic | Principal Proposed Change |
| Termination/CIC and golden parachutes |
|
| Pensions/deferred compensation |
|
| Risk and equity grant timing |
|
| Directors |
|
| eXtensible Business Reporting Language (XBRL) |
|
Termination & CIC: Qualitative Disclosure of Material Terms
The Proposal would eliminate the annual requirement to quantify potential payments and benefits under specified termination and change-in-control scenarios. Instead, companies would describe only the material terms of written and unwritten arrangements that provide payments or benefits in connection with such scenarios. The disclosure would be required for individuals who served as PEO or PFO during the last completed fiscal year.
The proposed rule would retain the ability to exclude arrangements that do not discriminate in scope, terms, or operation in favor of executive officers and are generally available to salaried employees. It would also permit omission of the disclosure if the company has already fulfilled the requirements in a Form 8-K filed under Item 5.02.
Pearl Meyer Observations on Modified Termination & CIC
Although companies would no longer need to annually calculate and present hypothetical termination payments under multiple scenarios, they would still need to identify and describe the material terms of all applicable arrangements. The focus will shift from scenario-based quantification to clear description of triggers, severance multiples, bonus treatment, equity acceleration, benefits continuation, tax gross-ups (if any), restrictive covenants, and other material contractual rights.
While the Proposal may reduce the need to prepare annual quantifications, it will not eliminate the ongoing need for a careful inventory of employment, severance, equity, and change-in-control arrangements. Also, coupled with the proposed reduction in the named executive officer (NEO) population to the PEO and PFO, the revisions could result in less visibility into significant termination and CIC benefits provided to other senior executives. Although some of these arrangements may be disclosed elsewhere, shareholders would no longer necessarily have a consolidated view of the potential payments and benefits available to the broader executive leadership team.
Golden Parachute Compensation—Consolidates the Table
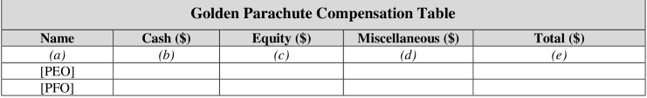
The Proposal would retain the separate golden parachute disclosure framework but streamline the table from eight columns to four by combining current columns for perquisites, tax reimbursements, other benefits, and related amounts into a single Miscellaneous column. Cash and equity columns would remain, together with a total. The population would generally follow the proposed PEO/PFO NEO definition. Narrative disclosure would also be streamlined, with an emphasis on material terms and payments in connection with the subject transaction.
Pearl Meyer Observations on Streamlined Golden Parachute Disclosure
The table may become easier to prepare and read, but the category-level detail currently visible in the separate columns may no longer be readily apparent. This simplification, along with the reduced NEO population, could make it harder for shareholders to understand exactly what top executives are receiving in connection with a transaction.
By combining several payment categories into a single “Miscellaneous” column, items such as excise tax gross-ups, enhanced retirement benefits, and other transaction-related payments would no longer be separately identified in the table. While companies would still need to disclose material information, shareholders could lose visibility into the types and magnitude of certain payments, making it more difficult to evaluate and compare golden parachute arrangements across transactions. As a result, companies will need to ensure that the accompanying narrative identifies all material components where those facts are important to an investor’s understanding.
Pension/Deferred Compensation: Eliminates Separate Tables
The Proposal would eliminate the Pension Benefits Table and Nonqualified Deferred Compensation Table. The SEC believes that the most material current-year pension and nonqualified deferred compensation information can be reflected in the Miscellaneous Compensation Received column of the Earned Compensation Table. Specifically, the table would include pension service costs and prior-service costs, company contributions or allocations to nonqualified deferred compensation plans, and above-market or preferential earnings on nonqualified deferred compensation.
The Proposal would not require separate disclosure of accumulated pension present value, years of credited service, aggregate nonqualified deferred compensation account balances, executive contributions, withdrawals or distributions in the current prescribed format.
Pearl Meyer Observations on Elimination of Retirement Tables
This is a meaningful reduction in tabular detail, particularly for companies with legacy defined benefit or supplemental retirement arrangements. However, companies should not assume that the economic value or material terms of these arrangements become irrelevant. Where a pension promise, deferred compensation arrangement, or unusual distribution is significant to the executive’s total compensation or contractual relationship, a principles-based narrative may still be appropriate.
Compensation Risk: Eliminates Item 402(s) Disclosure
The Proposal would eliminate Item 402(s), which currently requires disclosure, when applicable, of compensation policies and practices for employees if the risks arising from those policies and practices are reasonably likely to have a material adverse effect on the company. The existing rule includes examples of business units and incentive structures that may warrant attention and a list of topics that may be discussed, including risk assessment, short- and long-term incentives, adjustments to compensation policies and monitoring.
The SEC states that its staff has observed that Item 402(s) disclosure is often formulaic, typically stating that the compensation committee performed an annual risk assessment and concluded that no material adverse risk exists. The SEC believes that other Regulation S-K requirements, including MD&A and risk factors, will continue to elicit material information when compensation practices create material risks.
Pearl Meyer Observations on Elimination of Compensation Risk Disclosure
Eliminating the specific Item 402(s) disclosure requirement (which, as the SEC notes, has become boilerplate) does not eliminate the board’s or compensation committee’s responsibility to oversee incentive risk. Companies should continue their annual compensation risk assessment and retain supporting documentation. Material risk arising from compensation practices may still need to be discussed under other disclosure requirements, and the committee’s oversight responsibilities will remain relevant to good governance.
Equity Grant Timing: Eliminates Item 402(x)
The Proposal would eliminate Item 402(x), which requires disclosure of a company’s policies and practices regarding the timing of equity awards in relation to the release of material nonpublic information, including the timing of awards and the role of the board or compensation committee in determining award timing. The rule was adopted to address concerns about “spring-loading” and “bullet-dodging” and the potential for awards to be timed around material announcements.
Pearl Meyer Observations on Elimination of Equity Grant Timing Disclosure
The proposed elimination removes a discrete proxy disclosure obligation, not the underlying governance or legal considerations associated with equity award timing. Companies should continue to follow their insider trading policies, equity grant approval procedures, accounting controls, and exchange requirements. Boards and compensation committees should retain clear records of grant approvals and the basis for grant dates, particularly around material corporate announcements.
Director Compensation: Streamlines Quantitative and Narrative Disclosure
The Proposal would eliminate the prescribed tabular format for director compensation and replace it with a more principles-based disclosure requirement. It would retain separate quantification of cash retainers for different director roles and responsibilities and would require disclosure of cash compensation earned and the value realized on stock awards at vesting and options at exercise during the last completed fiscal year. The rule would no longer require prescriptive pension-related or nonqualified deferred compensation disclosure for directors. A general catch-all would require disclosure of other director compensation only when material, rather than the current enumerated list of “all other compensation” items.
The Proposal would continue to require disclosure of outstanding director equity awards, including the number of awards, grant date, vesting schedule, and material performance, market, or service conditions, although not with the same detail proposed for PEO/PFO equity awards. Narrative disclosure would describe the director compensation program and its material features. Where a director also serves as PEO or PFO, amounts paid solely for director service would be reported separately and not duplicated in executive compensation disclosure.
Pearl Meyer Observations on Streamlined Director Compensation Disclosure
This would give companies greater flexibility, especially where director compensation consists primarily of cash retainers and annual equity awards. Many companies may elect to retain a table voluntarily because it is familiar and facilitates comparison. We expect the more principles-based requirement to make director pay disclosures shorter, but companies should continue to explain material differences in retainers, committee chair fees, lead director fees, equity design, and any unusual compensation arrangements.
XBRL: Structured Data and Inline XBRL Changes
The Proposal would require large accelerated filers to tag the information disclosed in the Earned Compensation Table, Granted Compensation Table, and Status of Equity Awards Table in Inline XBRL. Other companies could tag the information voluntarily. The SEC does not propose block-text tagging or detailed tagging of footnotes or other narrative disclosure. It would also eliminate current Inline XBRL tagging requirements for PVP disclosure and clawback-related disclosure.
What Companies Should Be Considering Now
- Maintain an inventory of employment, severance, equity, and change-in-control arrangements, even if annual scenario-based quantification is eliminated.
- Maintain existing compensation risk assessments, equity grant approval controls, and clawback processes notwithstanding proposed changes to related disclosure requirements.
Concluding Thoughts
Reducing prescribed disclosure would not eliminate the underlying governance work. Companies would still need to maintain appropriate documentation and oversight for compensation risk, equity-grant timing, termination arrangements, and clawback decisions.
The SEC's proposal represents a meaningful shift in how executive compensation would be communicated to shareholders. While the Proposal could substantially reduce compliance costs and eliminate unnecessary disclosure, it also places greater responsibility on companies to determine what information is most relevant. The opportunity for compensation committees is not simply to disclose less, but to communicate more effectively about compensation philosophy, important decisions, and the relationship between executive pay and long-term shareholder value.
The Proposal would not affect the 2027 proxy season, and companies do not need to change their current disclosure practices. If adopted, the amendments would become effective on January 1 following publication of the final rules, with mandatory compliance beginning with the first full fiscal year ending on or after that date. In the meantime, companies can begin evaluating the potential implications for their compensation reporting and governance processes.